German CDU State Leader Quits After Election Rout Raises Policy Risk
Daniel Peters resigned after the CDU failed to enter a German state parliament for the first time, adding political uncertainty for investors watching Europe.
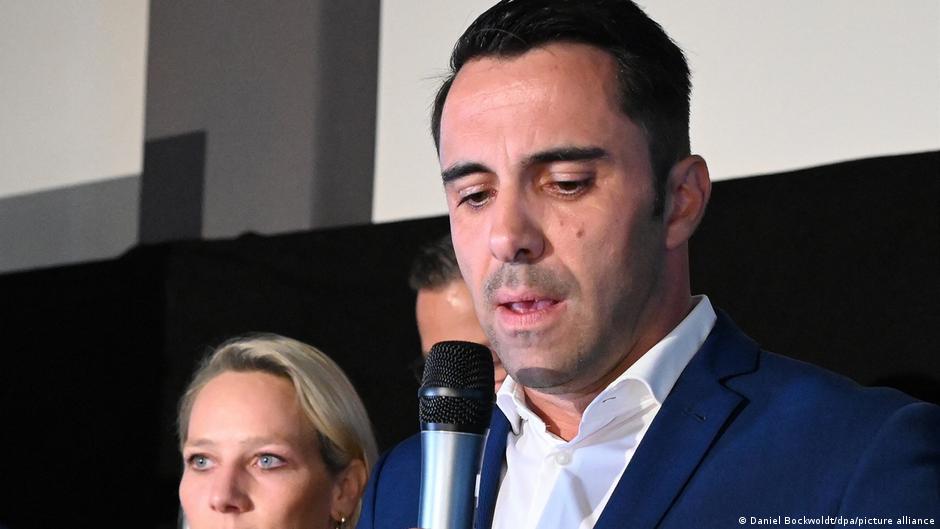
Daniel Peters, the head of the Christian Democratic Union in Mecklenburg-Western Pomerania, has resigned after taking responsibility for what he described as a crushing defeat in the state election. For capital markets, the result is less about one regional party official than about the broader signal it sends: Germany’s political center is under pressure, and investors are being reminded that electoral volatility can quickly become a factor in pricing European risk.
Peters, 45, stepped down after a meeting of the CDU’s state executive in Schwerin on Monday, September 21. He said he was personally assuming responsibility for the conservatives’ historic failure in the vote for the regional parliament. The CDU, the party of German Chancellor Friedrich Merz, won just 4.9% of the vote and, for the first time in the history of the Federal Republic of Germany, failed to enter the parliament of a federal state.
The immediate leadership role will be taken on temporarily by Philipp Amthor, 33, the state minister responsible for cooperation between Germany’s federal states and the federal government. Amthor said the Christian Democrats in Mecklenburg-Western Pomerania now need time to assess the result.
“It would be inappropriate in the current situation, and given the scale of this historic defeat, to immediately present an analysis or draw conclusions about the future balance of power,” Amthor said, according to dpa.
Political Shock Adds To Investor Watch List
The state election was won by the far-right Alternative for Germany, or AfD, which received 38.2% of the vote. The Social Democratic Party, led in the state by incumbent premier Manuela Schwesig, came second with 35.5%. The Left Party entered the regional parliament with 6.5%, while Alliance 90/The Greens won 5.7%. Other parties failed to clear the 5% threshold.
The SPD has already announced the start of talks with both parties that crossed the threshold in an effort to form a governing coalition without the AfD. That means the next market-relevant question is not whether the AfD topped the vote, but whether mainstream and left-leaning parties can assemble a workable administration. For investors, that distinction matters. Political fragmentation can weigh on sentiment even when the likely government excludes the most disruptive party.
There were no market prices or trading moves included in the source report, so the immediate reaction in German equities, bonds or the euro cannot be directly assessed from these facts alone. Still, the result lands in a setting where investors are already alert to fiscal policy, energy costs, defense spending, coalition stability and Germany’s longer-term growth outlook. A regional election does not set federal budget policy, but it can shape national political momentum, party strategy and perceptions of governability.
For equity investors, the implications are indirect but relevant. Germany’s listed companies depend on a predictable policy environment, especially in regulated sectors, infrastructure, energy transition investment and industries exposed to public spending. A weaker CDU in one state does not change corporate earnings overnight, yet the historic nature of the result may reinforce questions about how stable Germany’s traditional party system remains. That can affect the risk premium investors apply to policy-sensitive assets.
Bonds And Risk Premiums
For bond markets, the key issue is whether political fragmentation ultimately complicates fiscal decisions. German federal debt remains a benchmark for euro-area safety, and state-level politics rarely shift Bund pricing on their own. But repeated electoral setbacks for mainstream parties can become part of a wider narrative around policy execution. Investors in sovereign debt tend to care less about headlines than about whether governments can pass budgets, coordinate with federal authorities and sustain credible fiscal plans.
The CDU’s 4.9% result is especially notable because it fell below the threshold needed to enter the state parliament. In market terms, thresholds matter because they determine which parties can actually influence legislation and coalition formation. By missing representation altogether, the CDU loses a direct role in the regional parliament at a moment when the AfD has emerged as the largest party and the SPD is trying to construct a coalition excluding it.
That creates a political map in which the SPD, the Left Party and the Greens become central to the formation of government. The source report says the SPD has begun talks with both parties with the goal of forming a ruling coalition without the AfD. Investors will be watching whether those talks produce a durable arrangement or a prolonged negotiation. The shorter and clearer the process, the less likely it is to feed into broader concerns about German political stability.
For Chancellor Friedrich Merz, the regional result also carries a national message. The CDU’s failure in Mecklenburg-Western Pomerania comes under the leadership of a chancellor from the same party, even though state elections are shaped by local dynamics. Capital markets generally do not reprice a country based on one regional vote, but they do track whether governing parties retain the political capital needed to implement national policy. A historically poor result for the chancellor’s party therefore has significance beyond Schwerin.
The AfD’s first-place finish, with 38.2%, will likely intensify scrutiny of Germany’s political direction. Investors today are not being handed a new economic data point, but they are being handed a new political risk marker. The practical focus now shifts to coalition formation, the CDU’s internal response under interim state leader Amthor, and whether the federal party can contain the damage from a result that Peters himself framed as a devastating defeat.