Houthi Missile Attempt on Riyadh Adds New Risk Premium to Saudi Oil Flows
The intercepted attack and fresh pressure on Red Sea logistics sharpen investor focus on Aramco, energy supply routes and Gulf risk assets.
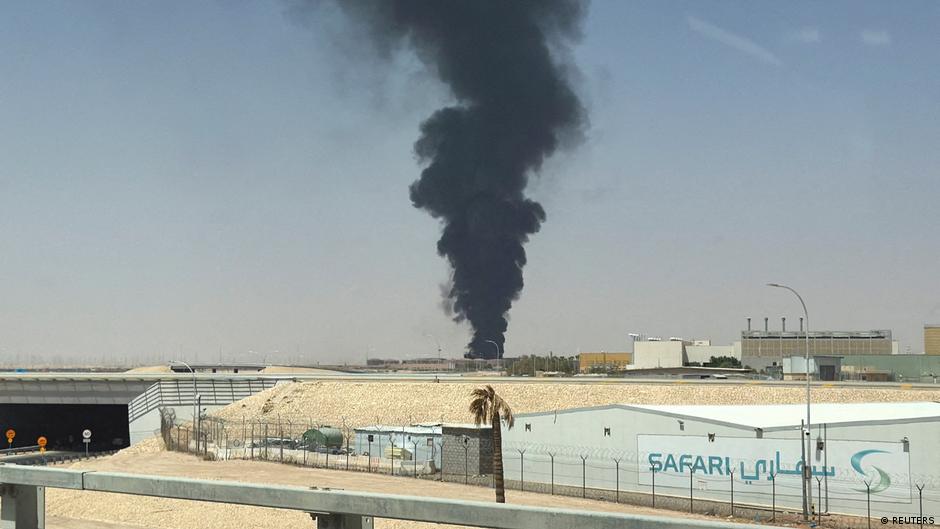
Saudi Arabia said Yemen’s pro-Iranian Houthi movement attempted to strike Riyadh with a ballistic missile overnight, an escalation that brings the kingdom’s capital directly into a widening conflict over energy infrastructure and Red Sea shipping routes. The missile was intercepted and destroyed, according to Brigadier General Turki al-Maliki, the official spokesman for the Saudi-led Coalition to Restore Legitimacy in Yemen.
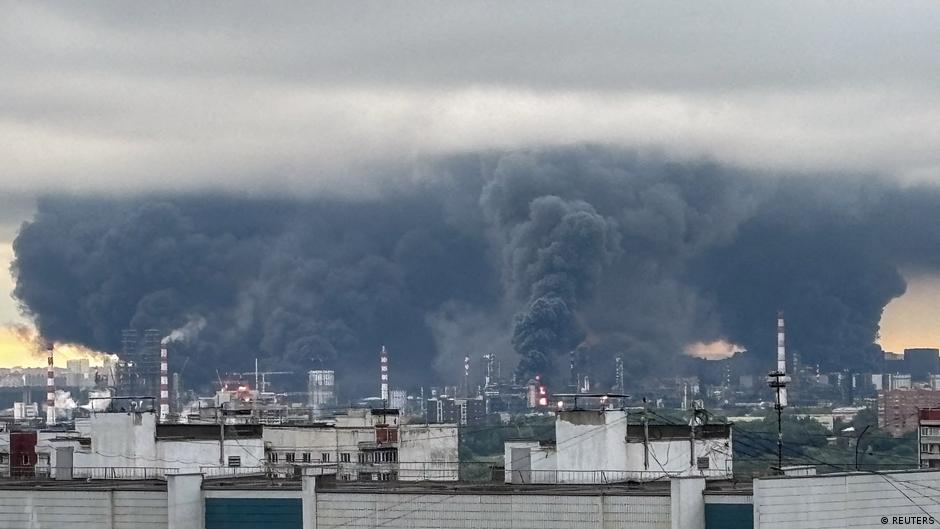
Air raid sirens sounded in Riyadh during the night, and some residents reported hearing an explosion. Saudi authorities reported no casualties or damage. Later, a plume of smoke was visible near the airport. AFP, citing its correspondent, said a fuel tank belonging to Saudi Aramco, the kingdom’s largest oil company, was on fire and that the blaze was extinguished. It remains unclear whether the incident was connected to the attempted missile strike. Aramco did not respond to journalists’ request for comment.
For investors, the incident adds to a sequence of disruptions around Saudi export infrastructure at a moment when alternative routes have become more important. Riyadh has relied increasingly on the East-West pipeline, which ends at the Red Sea port of Yanbu, after the war involving the United States and Israel against Iran significantly complicated tanker passage through the Strait of Hormuz.
Energy Infrastructure Returns to the Foreground
Saudi authorities also said the Houthis attempted to attack civilian infrastructure, including in the port city of Yanbu on the Red Sea, but that those attempts were thwarted. The Houthis, for their part, claimed they used drones, cruise missiles and ballistic missiles to strike “important facilities” in Riyadh and Aramco infrastructure in Yanbu.
Saudi Arabia said the ballistic missile aimed at Riyadh was “intercepted and destroyed,” while the Houthis claimed strikes on important facilities and Aramco infrastructure.
The competing claims could not be independently reconciled from the information available, but the market relevance is clear: attacks near Riyadh and Yanbu place Saudi energy distribution, refining and export reliability back at the center of geopolitical pricing. Even without confirmed physical damage from the Riyadh interception, the attempt underlines a broader vulnerability that may influence oil prices, energy equities, sovereign credit perceptions and regional equity risk premiums.
Earlier signs of pressure were already visible. On September 11, the Financial Times reported that Saudi Arabia had halted operations on the East-West pipeline after a drone attack launched from Iraqi territory. On September 18, Saudi Aramco notified at least two European refineries that it would not supply them with oil in October, Bloomberg reported. According to Bloomberg, the pipeline is expected to be partially restarted within days and fully restored within a month and a half.
Those timelines matter to traders because the East-West route has taken on greater strategic importance as Hormuz transit has become more difficult. A delayed restart would keep more attention on Red Sea logistics and could tighten perceptions of supply flexibility for buyers that depend on Saudi barrels. For refiners, the Aramco notifications also raise near-term procurement questions, particularly for European facilities that had expected October deliveries.
Red Sea Exposure and Market Sentiment
Recent Houthi activity has also reduced throughput along the route. In August, about 2.5 million barrels per day were shipped through Yanbu, the lowest level since 2013, the International Energy Agency reported. In recent weeks, capacity on the route has declined because of Houthi attacks on Saudi tankers in the Red Sea.
The maritime threat has expanded beyond individual vessels. On September 11, Reuters and AFP reported that the Houthis had captured strategically important islands in the Bab el-Mandeb Strait, which connects the Red Sea with the Arabian Sea. About 12% of global cargo traffic passes through the strait, including oil trade. Its importance for Saudi Arabia has increased after the closure of Hormuz. The Houthis said navigation through Bab el-Mandeb was “safe for all commercial vessels except Saudi ones.”
The previous day, it also became known that the Houthis had taken control of the port of Mocha on Yemen’s coast along the Bab el-Mandeb Strait. Reuters reported that the Houthi advance was being directed by Iran’s Islamic Revolutionary Guard Corps. Sources in Tehran said Iran was seeking to open a new front in its confrontation with the United States.
In capital markets, the immediate read-through is likely to be strongest in crude benchmarks, tanker risk, regional insurers, Gulf equities and Saudi-linked credit. A confirmed hit on Aramco infrastructure would carry more direct implications for supply and corporate operations, but even intercepted attacks can shift pricing when they occur near critical assets. Bond investors may also reassess geopolitical risk premia for Gulf sovereigns and state-linked issuers if attacks on Saudi territory become more frequent or more effective.
Saudi equities could face a more nuanced reaction. Defense-related spending and government backing remain supportive for domestic stability narratives, but repeated pressure on export infrastructure may weigh on investor appetite for sectors tied to logistics, petrochemicals and energy transport. For Aramco, the key issue is less a single unconfirmed fuel-tank fire than the cumulative risk around pipeline availability, refinery supply commitments and maritime access.
The coalition led by Saudi Arabia said on September 16 that the Houthis attacked the Muslim holy city of Mecca with a drone, which was shot down on approach. The Yemeni rebels denied the allegation. Taken together with the attempted Riyadh strike, the latest claims suggest the conflict is moving deeper into Saudi territory and closer to assets watched by global commodity and bond markets.
Investors now face a familiar but sharper Gulf equation: the physical supply shock has not been fully established, but the probability distribution around future disruptions has widened. Until the East-West pipeline returns to full operation and Red Sea shipping risks ease, markets are likely to keep a geopolitical premium attached to Saudi barrels and the securities most exposed to them.