German Economy Minister Warns Berlin Left Victory May Weigh on Investment
Katherina Reiche said the Left Party’s Berlin election success could damage Germany’s appeal to international investors and business.
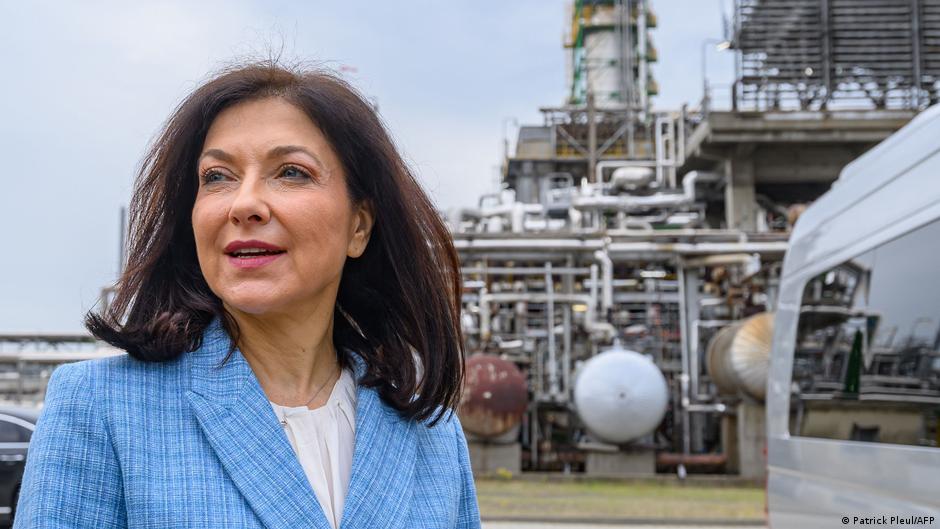
Germany’s economy minister has warned that the rising popularity of the Left Party could weaken the country’s investment appeal, injecting a political risk signal into a market already sensitive to Germany’s growth outlook, regulatory direction and property-rights framework.
Katherina Reiche, Germany’s economy minister and a member of the conservative Christian Democratic Union, said in an interview with Bild am Sonntag published in the early hours of Sunday, October 4, that the Left Party’s recent success in Berlin should be viewed not only as a local political result but as a broader warning for the German economy.
Her comments followed elections to Berlin’s House of Representatives, where the Left Party won with 25.7% of the vote. Reiche argued that the party’s platform, and the politicians advancing it in the capital, could undermine investor confidence in Germany as a place to deploy capital and operate businesses.
“What the Left Party stands for here in Berlin, and the people who represent them, is a danger not only for Berlin but for our entire country,” Reiche said. “It is a threat to Germany as a place for investment and business.”
For investors, the remarks place political risk squarely alongside Germany’s existing economic challenges. While the source article did not cite immediate moves in equities or bonds, Reiche’s warning is explicitly framed around the issues capital markets tend to price: property rights, business conditions, regulatory predictability and the willingness of foreign investors to commit long-term capital.
Property Rights Move to the Center of the Investment Debate
Reiche said international investors are watching closely to see how seriously Germany treats the protection of property and freedom. That point is likely to resonate with real estate investors, infrastructure funds, lenders and companies evaluating German operations, because the perceived stability of legal protections is a core input in financing decisions.
The minister singled out the Berlin Left Party’s plans to expropriate apartments from housing groups. That proposal, in her view, risks sending a signal beyond Berlin’s residential property market. Even when such policy debates are local, they can influence how investors assess the wider national environment for private ownership and business planning.
In capital markets terms, the concern is not only about one asset class. A debate over expropriation can affect the risk premium investors attach to German property companies, regulated businesses and any sector where political decisions shape future cash flows. If investors believe ownership rights may become less secure, they may demand higher returns, defer investment or shift capital to jurisdictions they consider more predictable.
Reiche’s comments also carry implications for bond investors. Germany’s reputation for institutional stability has long been part of its financial identity. While the source article does not report any immediate reaction in German government debt, political narratives that question the durability of property protections can become part of the broader macro conversation around competitiveness, investment and future growth.
A Warning Rooted in East German Experience
Reiche linked her criticism to her personal history, saying she was born and raised in the German Democratic Republic. She said she had seen first-hand how family businesses declined after nationalization and expropriation.
“I saw from my own experience how family businesses fell into decline after nationalization and expropriation,” she said.
The minister’s use of that history gives her warning a sharper ideological edge. She described expropriation, socialism and communism as paths that lead to impoverishment, hardship and totalitarianism. She added that expropriation has never worked anywhere on the planet.
Those statements are political, but they also speak to a central investor concern: the relationship between state power and private capital. For shareholders and creditors, the predictability of policy is often as important as the policy itself. Sudden or sweeping changes to ownership rules can alter asset valuations, disrupt financing models and increase uncertainty across sectors.
The Berlin result therefore matters beyond party politics. A 25.7% vote share for the Left Party in the capital gives greater visibility to policy positions that critics say could damage Germany’s business climate. Reiche’s intervention suggests that senior figures in the federal government view the election outcome as a potential warning sign for the national investment story.
Germany is still regarded as one of Europe’s core economies and a major destination for international capital. But Reiche’s remarks underscore how quickly political developments can become market-relevant when they touch property rights, housing policy and business confidence. Investors assessing Germany today may now weigh not just macroeconomic data and corporate earnings, but also the political momentum behind more interventionist approaches in Berlin.
For equity investors, the most direct read-through is to sectors exposed to regulation, housing policy and long-duration capital commitments. For bond investors, the issue is less about an immediate fiscal shock than about the longer-term credibility of Germany’s institutional and economic model. For companies, the question is whether political support for expropriation proposals remains contained or becomes part of a wider debate over the role of the state in the economy.
Reiche’s warning does not itself change policy. It does, however, sharpen the market narrative around Germany’s investment climate after the Berlin vote. Her message to investors was clear: political outcomes in the capital may influence perceptions of Germany’s reliability as a place to own assets, build businesses and allocate capital.